$0 down on a metal roof is financing — not a free roof. See if a program may apply to your household.
Some metal-roof installers advertise $0 down through a lender, and some of those offers look at military or veteran households first. That is a credit product. It is not a government grant, not a VA benefit by default, and not an approval. This page sends you to a third-party form so a participating provider can see whether you might qualify.
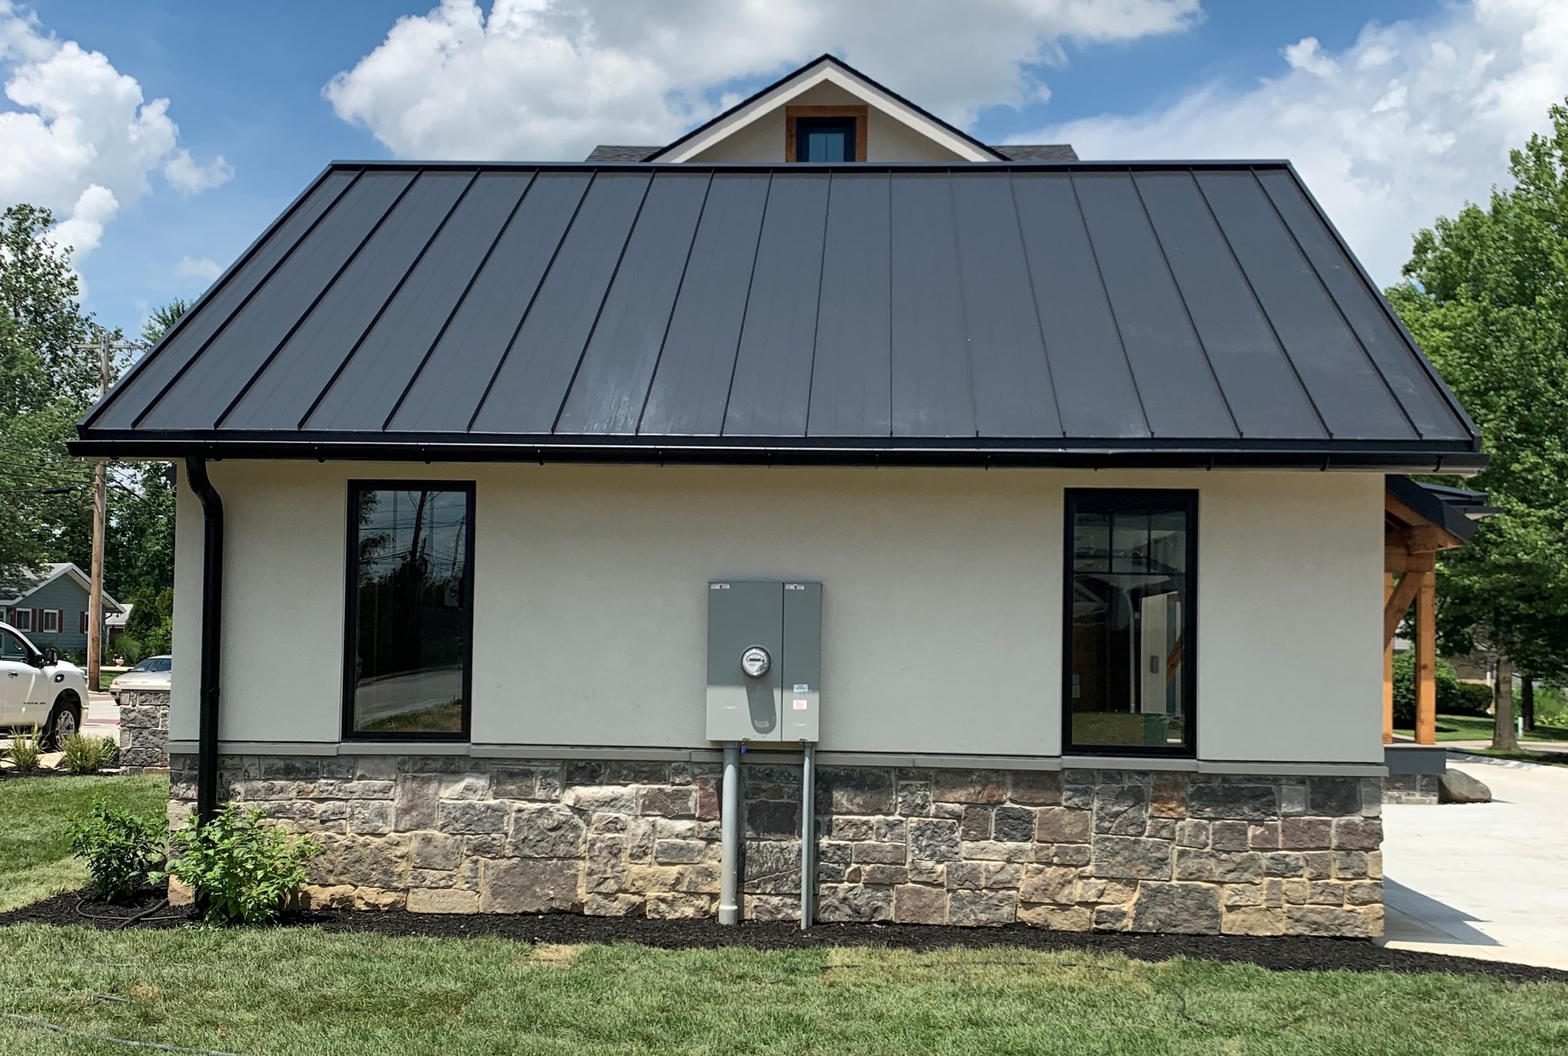
Metal usually costs more up front than asphalt. The pitch is often lifespan and fewer reroofs — not a locked price or a locked monthly payment.
What “$0 down” actually is
$0 down means a lender may finance the project so you do not write a large check on day one. You still repay principal and interest on a schedule. APR, term, dealer fees, and whether the payment is deferred all sit in the contract — not in a headline.
Whether $0 down exists for a given house is a lender and installer question. Credit, income, and the project itself decide. This page is not a rate sheet.
$0 at signing is not $0 over the life of the loan. Ask for APR, term, and total of payments.
Income, credit, debt ratio, and property type can stop an application. Some programs also screen military status.
The form you will open is labeled around a military $0-down path. Service status may be asked. It does not create a VA entitlement by itself.
Panel, pitch, tear-off, and access change the invoice. This page does not publish a per-square-foot price.
Check this $0-down metal-roof path
The next page is run by a participating provider. They can tell you whether a $0-down option is even on the table for your file.
See if you qualify for $0 down Takes a few minutes · You can leave without booking workWhy metal shows up in the pitch
Standing-seam and similar systems are sold on service life, weather performance, and fewer tear-offs over a long stretch. Those claims belong on the spec sheet and the warranty, not as a number this advertisement can assign to your house.
Some insurers advertise credits for certain roof types. Carriers set those credits. Do not fold an insurance cut into loan math until your agent confirms it in writing.
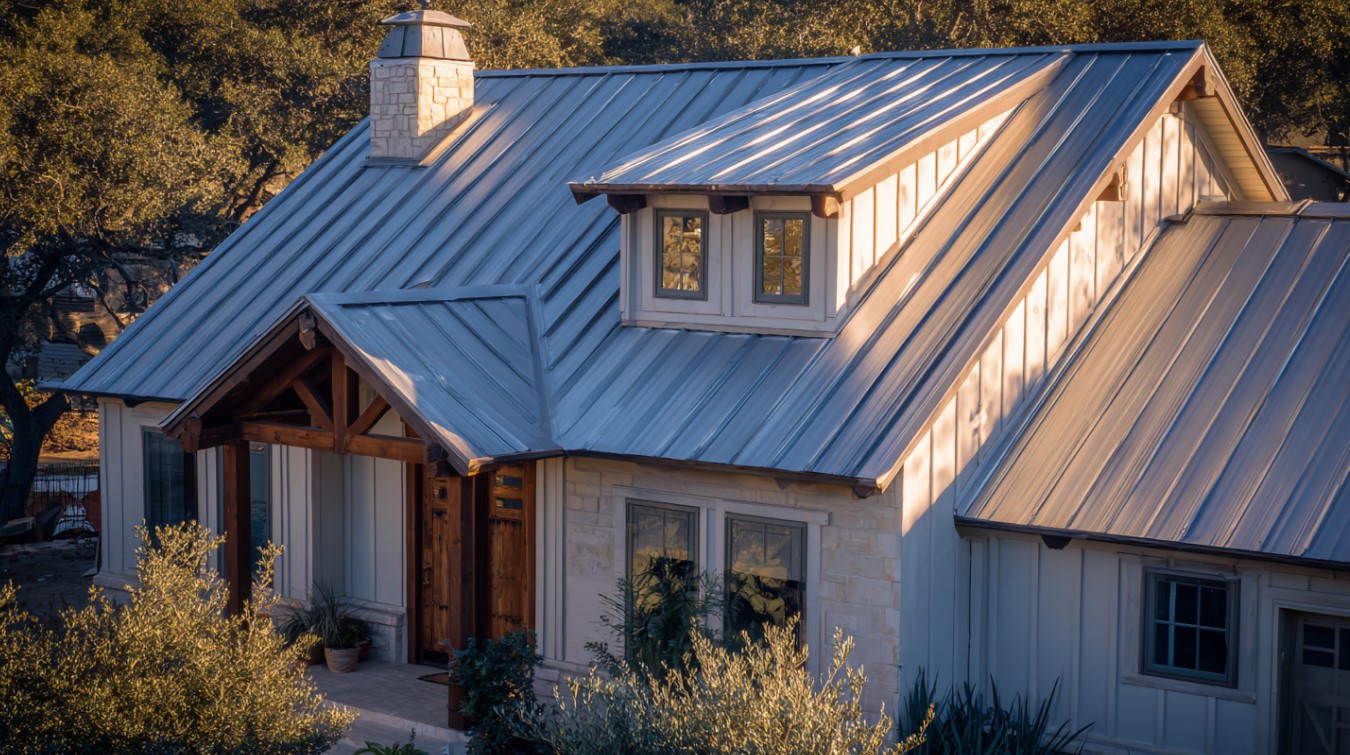
Color, panel profile, and underlayment change both look and price. A photo is not a bid.
Questions to ask before you sign a $0-down ticket
- Is the $0 down a loan, a promotional deferral, or a contractor float?
- What APR and term are you actually being offered after a hard or soft pull?
- Is a dealer fee rolled into the project price?
- Does military or veteran status change the product — and can you document it?
- What happens if the roof needs decking repair the original number omitted?
- Who warrants labor vs. the panel manufacturer?
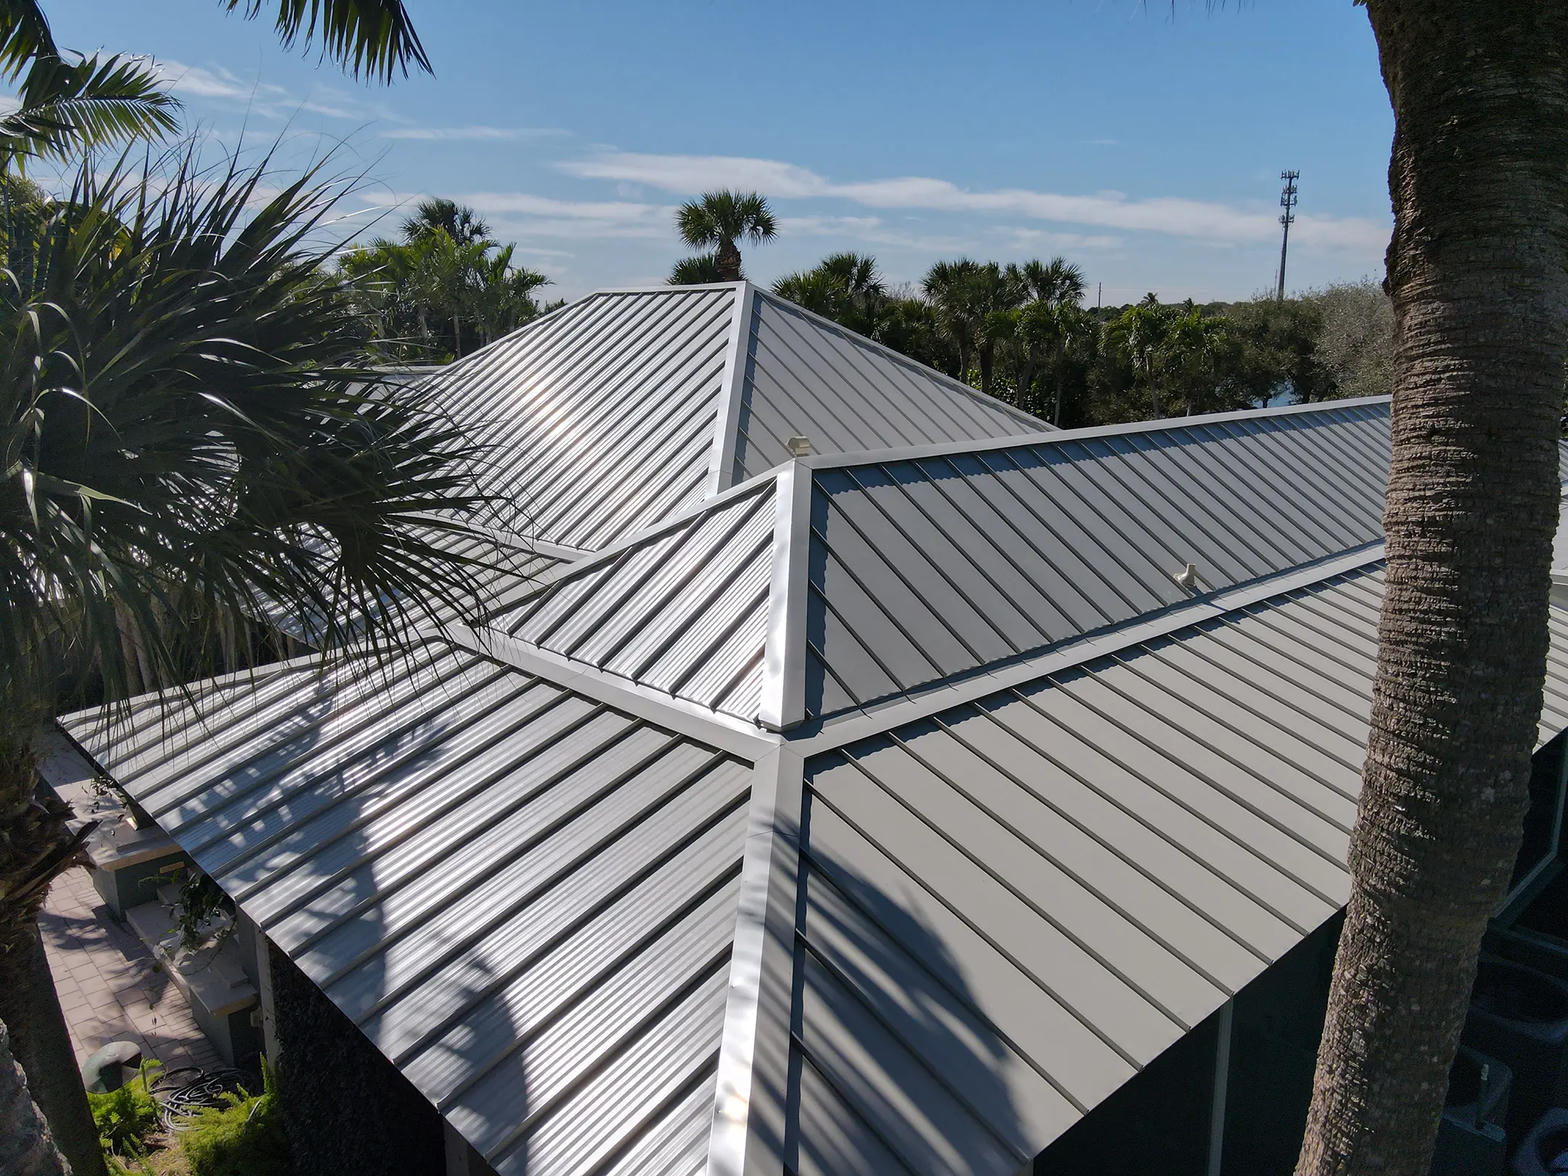
Seams, flashing, and ventilation decide whether the system sheds water. Financing does not.
After you click
You leave Roof Repair Quote Help and go to getmetalroofinginnovations.com. That operator may collect contact details and run a credit or eligibility screen. Someone may call. This site does not install roofs, does not lend money, and does not decide whether you qualify.
FAQ
Does $0 down mean the roof is free?
No. It means a lender may fund the work so you start with no cash down — if you are approved. You still owe the loan.
Do I have to be in the military?
The destination URL is built around a military $0-down path. Ask on the form. Civilian households may or may not have a separate product. Neither path is guaranteed here.
Is this a government program?
No. This page is an advertorial for a private estimate/financing offer. It is not VA, HUD, or FEMA.
Will metal cut my electric bill by a set amount?
No amount on this page is guaranteed. Reflective coatings can change attic heat. Results depend on insulation, climate, and HVAC.
See whether $0 down is on the table
Approval, APR, and installation are decided after the form — not on this article.
See if you qualify for $0 down Subject to credit and installer availability